China's Footprint in Africa: The Good, The Bad, and The Ugly
By Joseph Sampson · · 9 min read
For two decades, the most important infrastructure decision in Africa was not made in Washington, London, or Paris; it was made in Beijing, and the continent's railways, dams and skylines still carry its signature.
In 2000, when the Forum on China-Africa Cooperation was created, China-Africa trade stood at about $10 billion, yet by 2023 it had reached $282 billion. More than 10,000 Chinese firms now operate across the continent, from the Tecno phone shop in Accra to the cranes rising over Egypt's new capital in the desert, and no external power has moved this fast, or this visibly, in Africa's modern history. To understand this transformation, one has to hold three contradictory truths at once, each of them partial and all of them true.
I. The Good: What China Built
The West largely stopped building hard infrastructure in Africa in the 1990s, as aid shifted toward governance, health, and education; these were noble causes, but they do not generate megawatts, and into that vacuum China returned to concrete.
A traveller who boards a train in Addis Ababa rides a $4 billion Chinese-built electric railway to Djibouti, a line that cut freight time to the sea from three days to about 12 hours.
During dumsɔ, the dark had weight; a sweltering night where the fan dies mid-spin, your room turns to an oven, and the entire street goes quiet except for the thin whine of mosquitoes around your ears and the choking cough of generators fighting to stay alive.
Into that dark in Ghana, the Bui Dam came online, adding 400 megawatts financed by China Exim Bank, and it was followed by the Chinese-built Atuabo gas plant, which within weeks of starting up had the Aboadze power station running entirely on Ghanaian gas.
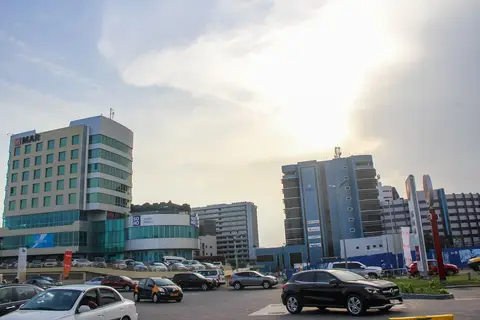
On Egypt's Suez Canal stands TEDA, a Chinese industrial zone grown into a town of factories, with about 180 companies and more than $3 billion invested, producing fiberglass, dishwashers and air fryers made not for China, but for Egypt and the markets beyond. East of Cairo, China State Construction is pouring the Chinese-financed business district of the new capital, crowned by the Iconic Tower, the tallest building in Africa.
This is the part of the story Beijing likes to tell, and it is true: Boston University counts $170 billion in Chinese loans to Africa between 2000 and 2022, most of it directed to energy and transport.
There is also a second, quieter good, which is affordability: Transsion, a Shenzhen company no one in the West knows, owns Tecno, Infinix and Itel, and it understood something that Apple and Samsung did not, that Africans needed dual SIM cards and a battery that lasts three days. Today it sells about half of Africa's smartphones, and a $60 smartphone is not a footnote; it is how a trader in Cape Coast reaches mobile money.
China also builds fast, and for a president who needs a road completed before an election, that speed is not a detail; it is the whole point.
II. The Bad: The Structure That Traps
Yet look at what moves on those roads and railways: in 2023, Africa sold China $109 billion worth of goods, mostly crude oil, copper, cobalt and iron ore, exported unprocessed and priced in London and Shanghai, while it bought back $173 billion, mostly machinery, electronics, vehicles and textiles, leaving a record gap of $64 billion.
This is a colonial trade pattern with new partners: when commodity prices soar, Accra and Luanda boom, and when prices crash, as they did in 2015-16, those same economies collapse. That volatility is no accident; it is the architecture, as the experience of three countries illustrates.
In South Africa, the continent's most industrialized economy, the story is one of deindustrialization: the Southern African Clothing and Textile Workers Union blamed some 62,000 lost jobs on the surge of Chinese imports that began in 2003, and although Coega, in the Eastern Cape, finally secured its R11 billion BAIC auto plant, production only began in 2024, when Chinese-built cars were already crowding the market.
In Ghana, the wound is visible: in the mid-1970s, the country had 16 textile factories employing more than 25,000 people, and their wax prints, GTP's famous among them, were cultural markers, worn to weddings and funerals and named like proverbs. Today only a handful survive, and although the patterns still hang in Makola Market, many were copied in China and shipped back at a fraction of the price.
Then there is debt, for the innovation that made all this building possible was resource-backed lending, the Angola Model. Angola signed $42.6 billion in Chinese loans, much of it to be repaid not in dollars but in barrels of oil, an arrangement that seemed clever when oil traded at $110 a barrel in 2012. When oil sank to about $30 in early 2016, however, Angola had to ship more barrels to service the same debt, because such loans are procyclical, making booms bigger and busts deeper.
Ghana borrowed in the same way, securing part of the Bui Dam loan against cocoa sales. When Ghana defaulted in 2022, owing China $1.9 billion, it entered the G20 Common Framework, and it took 18 months, until June 2024, to sign a deal, partly because China is not in the Paris Club and preferred longer maturities to haircuts.
Beijing has never seized a strategic asset in Africa, and the 2018 rumour that it would take Zambia's main airport proved false, but it has never needed to, because the opacity does the work. AidData found that every Chinese loan contract it examined after 2014 carried confidentiality clauses, often barring the borrower from revealing the terms, and a nation cannot debate a debt it is not allowed to read.
III. The Ugly: Where the Footprint Turns Toxic
If the Bad is structural, the Ugly is human, and its costs fall on rivers, workers and communities rather than on treasuries.
Between 2008 and 2013 an estimated 50,000 Chinese small-scale gold miners poured into Ghana; private migrants rather than parties to any state deal, they drove excavators into forest reserves and rivers until, in 2013, a state task force deported 4,592 of them. Yet the trade they helped to mechanize, galamsey, did not leave with them, and scientists at the CSIR now report that more than 60% of Ghana's water bodies are polluted by illegal mining, and Ghana Water has shut treatment plants at Daboase and Kyebi because the water was too thick to treat; the Pra runs brown.
In the Democratic Republic of Congo, which mines about three quarters of the world's cobalt, the metal in many electric car batteries, Chinese firms control about two thirds of that output, and Amnesty International has traced child labor from artisanal pits into global supply chains.
At the Collum coal mine in Sinazongwe, Zambia, in 2010, two Chinese managers opened fire on miners protesting over pay, wounding 11, and the image stuck.
The backlash is real, and this year Ghana's traders' union, GUTA, has threatened to shut foreign-owned shops, Chinese among them, in Kumasi and in Accra. Some will call this xenophobia, but it is also what happens when small traders who employ five people must compete with a supply chain that brings a container from Yiwu to Tema in weeks, at a price they cannot match.
IV. The Missing Variable: African Agency
The mistake, however, is to paint Africa as a victim, because outcomes diverge widely according to how African governments bargain.
Egypt is the strategist: it owes China about $9.6 billion, but it owes the IMF and the Gulf far more, and it handed Siemens an €8 billion power deal. It never became dependent on any single lender, preferring instead to court and use them all.
South Africa is the regulator, and when cheap steel flooded its market, it imposed safeguard duties. It accepted the BAIC investment but made the state a partner, with the Industrial Development Corporation holding 35% of the plant, and it has used BRICS not as allegiance, but as leverage.
Ghana is the late reformer, which in 2017 sent in Operation Vanguard, the military-police teams that burned excavators, and in 2020 passed mining local content regulations that reserve key services for Ghanaians and cap expatriate staff. They came too late for the Pra, but not too late for the next lithium deal.
The sharpest lesson of all comes from Zimbabwe, which in 2022 banned exports of raw lithium. Within a year, Huayou had built a $300 million processing plant near Harare, which suggests that when an African government asks firmly, the factory comes.
Conclusion: From Lending to Investing
The era of big loans is over, as the sequence of pledges makes plain: FOCAC 2018 pledged $60 billion, FOCAC 2021 pledged $40 billion, and FOCAC 2024 pledged about $50 billion, most of it still credit, but now presented as investment, green energy and "small and beautiful" projects. Beijing has learned what Accra learned before it: debt distress hurts Chinese banks as surely as it hurts African treasuries.
The next chapter therefore turns on what Africa asks for, and the African Continental Free Trade Area, with 1.4 billion people in a single market, finally gives the continent the scale to ask. Three demands would change the terms of the relationship: first, African governments should publish every loan, every rate and every collateral clause, so that parliaments know what they are signing; second, they should insist on processing at home, so that cobalt, lithium and bauxite leave the continent as metal rather than ore; and third, they should enforce the local-content laws already written, with the African Union holding the line so that no capital can be played against another, because if you want to sell to Africa, you must make in Africa.
For two decades, Africa's most important infrastructure decisions were made in Beijing, and the road, the dam, and the port were the first chapter of that story; whether the factory follows will be the second, and the pen for that chapter lies in Addis Ababa, Accra, Cairo and Pretoria, not in Beijing.
Views expressed are the author's own and do not necessarily reflect AfricaFrontPage's.
Have an argument to make? Write for AfricaFrontPage ›